
Our five-year view: a selective recovery led by affordable, well-connected homes. Explore price scenarios, demand drivers and the areas Baytii would investigate first.
Our view for the next five years
We expect Türkiye’s housing market to recover selectively as inflation and borrowing costs ease. The stronger case is for reasonably priced homes near employment and operating transport, with running costs local households can afford. A nationwide rise in lira prices is much easier to envisage than every property delivering a strong dollar return.
For 2026–2027, we would prioritise negotiation, usable housing and rental cash flow. If credit becomes more affordable, 2028–2031 could bring a wider resale audience. This favours buying a competitive unit before demand broadens, rather than paying today for several years of hoped-for appreciation.
The starting point: prices are rising, but purchasing power is under pressure
In July 2026, residential prices rose 25.0% year on year in lira nationally, 27.7% in Istanbul and 26.6% in Ankara. National prices nevertheless fell 5.1% after inflation. This is a market where nominal price growth can coexist with room to negotiate and weak real returns. [1]
July sales totalled 123,603, down 17.0% annually, while mortgaged sales rose 23.7%. January–July sales were still down 5.5%. Foreign buyers accounted for 2,120 July purchases—about 1.7% of the total. Domestic affordability and credit therefore matter more to the broad market than overseas demand alone. [2]
What could property prices look like in 2031?
Our central case is gradually slower nominal growth as inflation falls, with modest real appreciation in well-selected stock. The table compounds explicit annual price assumptions for 2027–2031 from an end-2026 starting value. The stronger case needs easier credit and resilient household demand; the weaker case assumes affordability remains stretched and competing supply limits pricing power.
For the real comparison, every case uses inflation assumptions of 15%, 9%, 5%, 5% and 5%. The first two follow CBRT’s 2027 and 2028 forecasts; the final three extend its medium-term 5% target as our modelling assumption. These are sensitivity scenarios, not probability-weighted forecasts. Rent, tax and transaction costs are excluded from the price changes. [3]
Three price paths to 2031
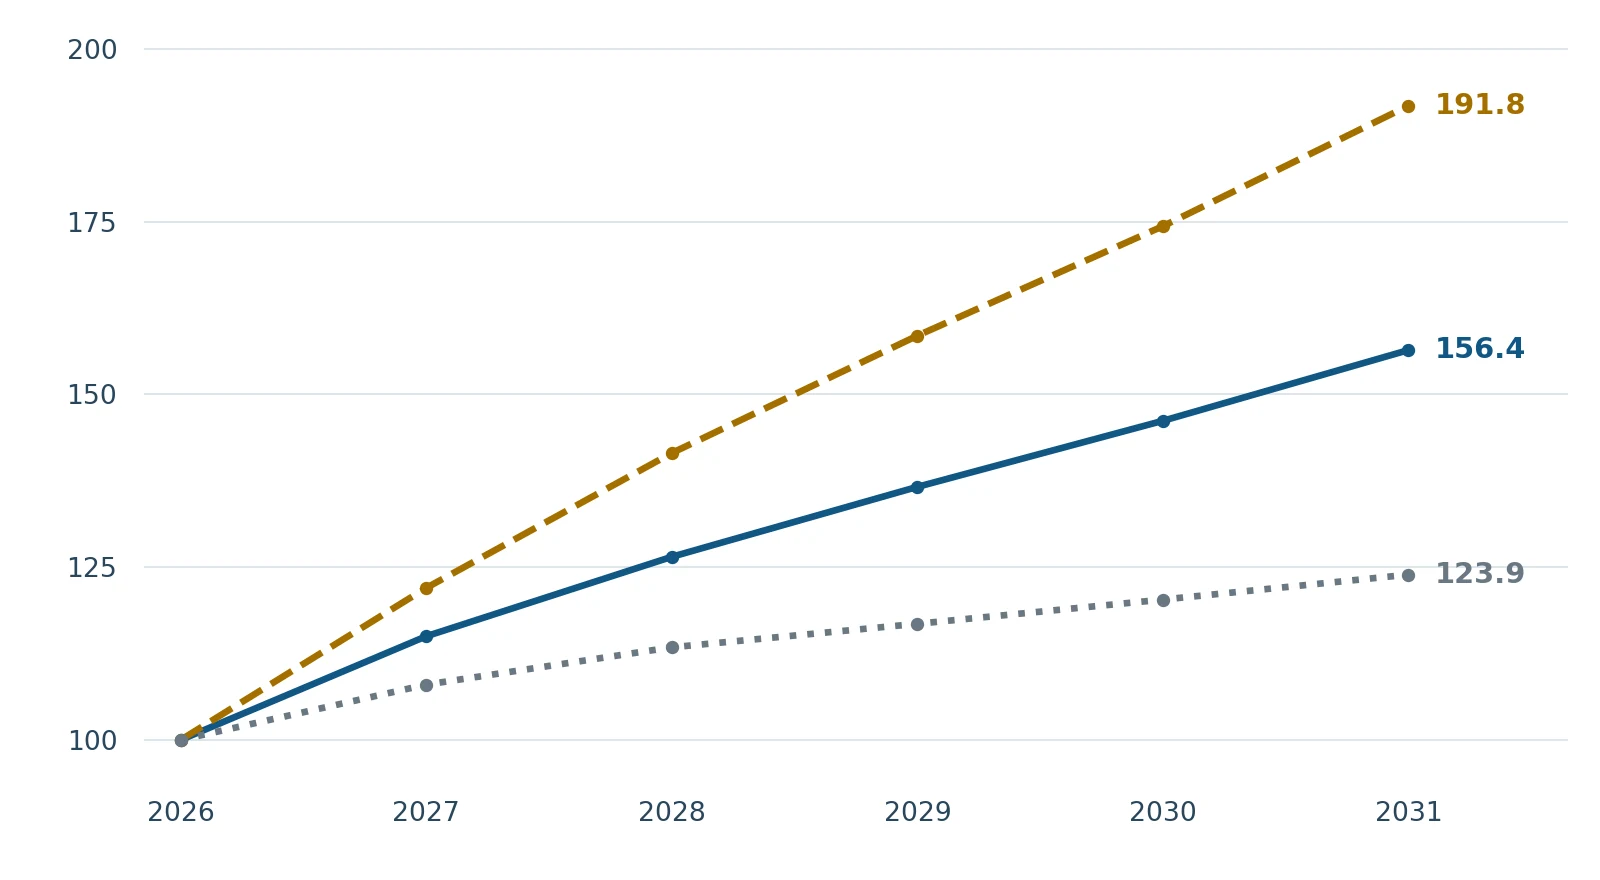
- Gradual recovery · central case
- Faster recovery
- Affordability stays weak
| Scenario | Annual price assumptions: 2027 / 2028 / 2029 / 2030 / 2031 | Five-year lira price change | Five-year real price change |
|---|---|---|---|
| Gradual recovery · central case | 15% / 10% / 8% / 7% / 7% | +56.4% | +7.8% |
| Faster recovery | 22% / 16% / 12% / 10% / 10% | +91.8% | +32.2% |
| Affordability stays weak | 8% / 5% / 3% / 3% / 3% | +23.9% | -14.6% |
Which homes could attract the strongest demand?
Our first filter is practical 1+1 and 2+1 apartments near jobs and reliable transport: a lower total ticket can reach more tenants and eventual buyers than a large luxury unit. For family districts, efficient 2+1 and 3+1 layouts, schools, storage and predictable monthly charges may matter more than a long amenities list.
We would favour documented building quality and useful layouts over age or branding alone. Larger resort properties can suit lifestyle buyers, but their tenant and resale audience is narrower. Test year-round local demand before using holiday-season rents to justify the purchase price.
Areas to investigate first—and the reason for each
This is a research shortlist, not a league table of future price winners. Istanbul offers distinct transport and employment catchments; Ankara and Antalya provide different tenant profiles. Compare streets and buildings within each area, including completed competing supply.
For the July 2026 city comparison, Istanbul’s 27.7% and Ankara’s 26.6% annual price growth exceeded İzmir’s 23.1%; these past figures do not establish the next five years’ winner. At neighbourhood level, we would investigate the following demand mechanisms before choosing a unit. [1]
| Area | Demand mechanism to investigate | Property starting point | What could limit growth |
|---|---|---|---|
| Ataşehir–Ümraniye, Istanbul | Employment catchments and the M12 line under construction | Practical apartments with verified access to jobs | Delivery timing and a transport premium already in the price |
| Kartal–Pendik, Istanbul | Operating M4 metro and airport connection | 1+1 or 2+1 within a genuine walk of a station | Competing towers and high service charges |
| Halkalı–İkitelli, Istanbul | Operating M9 connections and employment access | Functional family apartments near the actual route | A district address does not guarantee a short commute |
| Çankaya, Ankara | Local professional and family rental demand to verify | Well-located 2+1 or 3+1 with manageable costs | Building condition, entry price and local rent evidence |
| Konyaaltı, Antalya | A mix of residential and lifestyle demand to verify | Homes that work for year-round occupation | Seasonality, competing supply and dependence on foreign buyers |
Which Türkiye area fits your five-year plan?
Share your budget, funding currency and intended purchase date. Ask Baytii for a focused area shortlist, current property comparisons and the rental evidence behind each choice.
Request my Türkiye shortlistRental income and dollar returns: keep the two calculations separate
The new-tenant rent index rose 28.4% nationally in July 2026, but fell 2.6% after inflation. Rent can support ownership while waiting for resale, yet affordability limits how far rents can rise. Use achievable long-term rent, vacancy and owner costs to assess the selected property. [1]
A 56.4% lira price increase alongside a 50% rise in the TRY-per-dollar exchange rate would produce only about 4.3% dollar price growth over five years, before income and costs. The calculation is 1.564 ÷ 1.50 − 1. For the purchase budget, net rental yield and one-home-versus-two comparison, use our separate buying guide.
Buying Property in Türkiye: Budget, Residency and Rental Yield
Buy now or wait? Watch three signals
Buying now makes sense when the negotiated price compares well with completed alternatives, the property serves your goal and you can comfortably hold it. Waiting is more useful when your chosen project already prices in unbuilt infrastructure, your funding is uncertain or nearby deliveries could create better choice.
Review three signals: whether mortgage activity recovers beyond one month; whether local rents and sale prices improve after inflation; and whether nearby completions are being absorbed. Improving credit with controlled local supply supports the stronger scenario. Weak household purchasing power plus rising vacancies supports the weaker one.
Turn the outlook into a shortlist you can act on
Start with the funding currency, total budget, rental or personal-use goal and holding period. Then compare two or three areas using the same unit size, building standard and total-cost basis. An attractive district story should translate into a price, rent and resale audience for a specific home.
Ask Baytii to show current written offers, cash and instalment terms, operating costs, dated rental evidence and the checks still required. Use the outlook to choose where to investigate; use the buying guide to decide which property deserves a viewing and detailed review.
Buying Property in Türkiye: Budget, Residency and Rental Yield
Questions about Türkiye’s five-year property outlook
Will property prices in Türkiye rise over the next five years?
Our central view is rising nominal lira prices with a selective recovery in real values. The central scenario compounds to approximately 56% nominal growth and 8% real growth from end-2026 to end-2031 under its stated assumptions. It is a decision framework; a particular home can perform very differently.
Will Turkish property become more valuable in dollars?
That depends on both the lira sale price and the exchange rate. If the lira price rises more slowly than TRY per dollar, the dollar value falls. Compare your expected rent, costs and exit proceeds in the currency that matters to you.
Which areas have the strongest growth potential?
We would first investigate employment and transport catchments in Ataşehir–Ümraniye, Kartal–Pendik and Halkalı–İkitelli, with Çankaya and Konyaaltı as different demand cases. Their appeal depends on entry price and building-level evidence, not the district name alone.
What apartment types could be easiest to rent and resell?
Our starting point is an efficient 1+1 or 2+1 near transport and work; family areas may favour 2+1 and 3+1. Compare the full monthly occupancy cost with local household budgets. A broad local audience can help both letting and resale.
Is 2026 a good time to buy, or should I wait?
Use the negotiated price and your ability to hold the property as the decision points. A ready home with credible rent can work before a broad recovery. If the price already assumes future infrastructure gains, compare completed alternatives or wait for stronger evidence.
Will a new metro line automatically increase prices?
Better access can broaden demand, but the benefit may already be reflected in asking prices. The M12 is under construction; M4 and M9 are operating. Check actual walking distance, interchanges, delivery status and the premium over comparable homes.
How should I choose between ready property and off-plan for this outlook?
A ready home lets you inspect and potentially earn rent earlier. Off-plan may offer staged payments but adds delivery timing and a period without rent. Compare the total price and the value of foregone rent before using future market growth to justify either option.
Sources and analysis method
Reviewed 14 September 2026. Observed prices and rents: CBRT, July 2026; sales: İş Investment’s analysis of TurkStat releases; inflation: CBRT, August 2026. The scenario rates and area shortlist are Baytii’s editorial assumptions, not official property forecasts or a statistical ranking. Scenarios start at end-2026; source links and transport status were checked on the review date.